
Listen to this Insight
Executive Summary
The outlook for government policy, bond markets, and monetary policy appears less settled than it has been for much of the post-COVID period. The debate about public debt, the functioning of the Treasury market, inflation persistence, and the future path of interest rates has intensified. Global bond yields have been soaring.
Central banks are starting to react, with markets currently signaling a broader cycle of potential rate changes across several major economies, both in the medium term and possibly well into 2027. For investors, this matters because changes in monetary policy can have a powerful influence on returns across equities, bonds, currencies, and commodities. In particular, uncertainty around monetary policy during periods of heightened central bank activity has historically been more challenging for equities, with bonds faring little better. Macro strategies, however, are designed to attempt to benefit during such uncertainty.
This paper considers why global monetary policy uncertainty may currently be elevated, how it can be measured, and why uncertainty may persist. Further, the paper shows how key assets and macro strategies have behaved across higher- and lower-uncertainty regimes and have proven useful diversifiers.
Bond Markets Appear Nervous
Global bond markets are under pressure. Inflation has remained stubbornly high across much of the developed world. At the same time, elevated public-debt levels and heavy sovereign issuance have returned to the center of market debate. All of this has been driving bond yields higher.
Exhibit 1: Yields have been soaring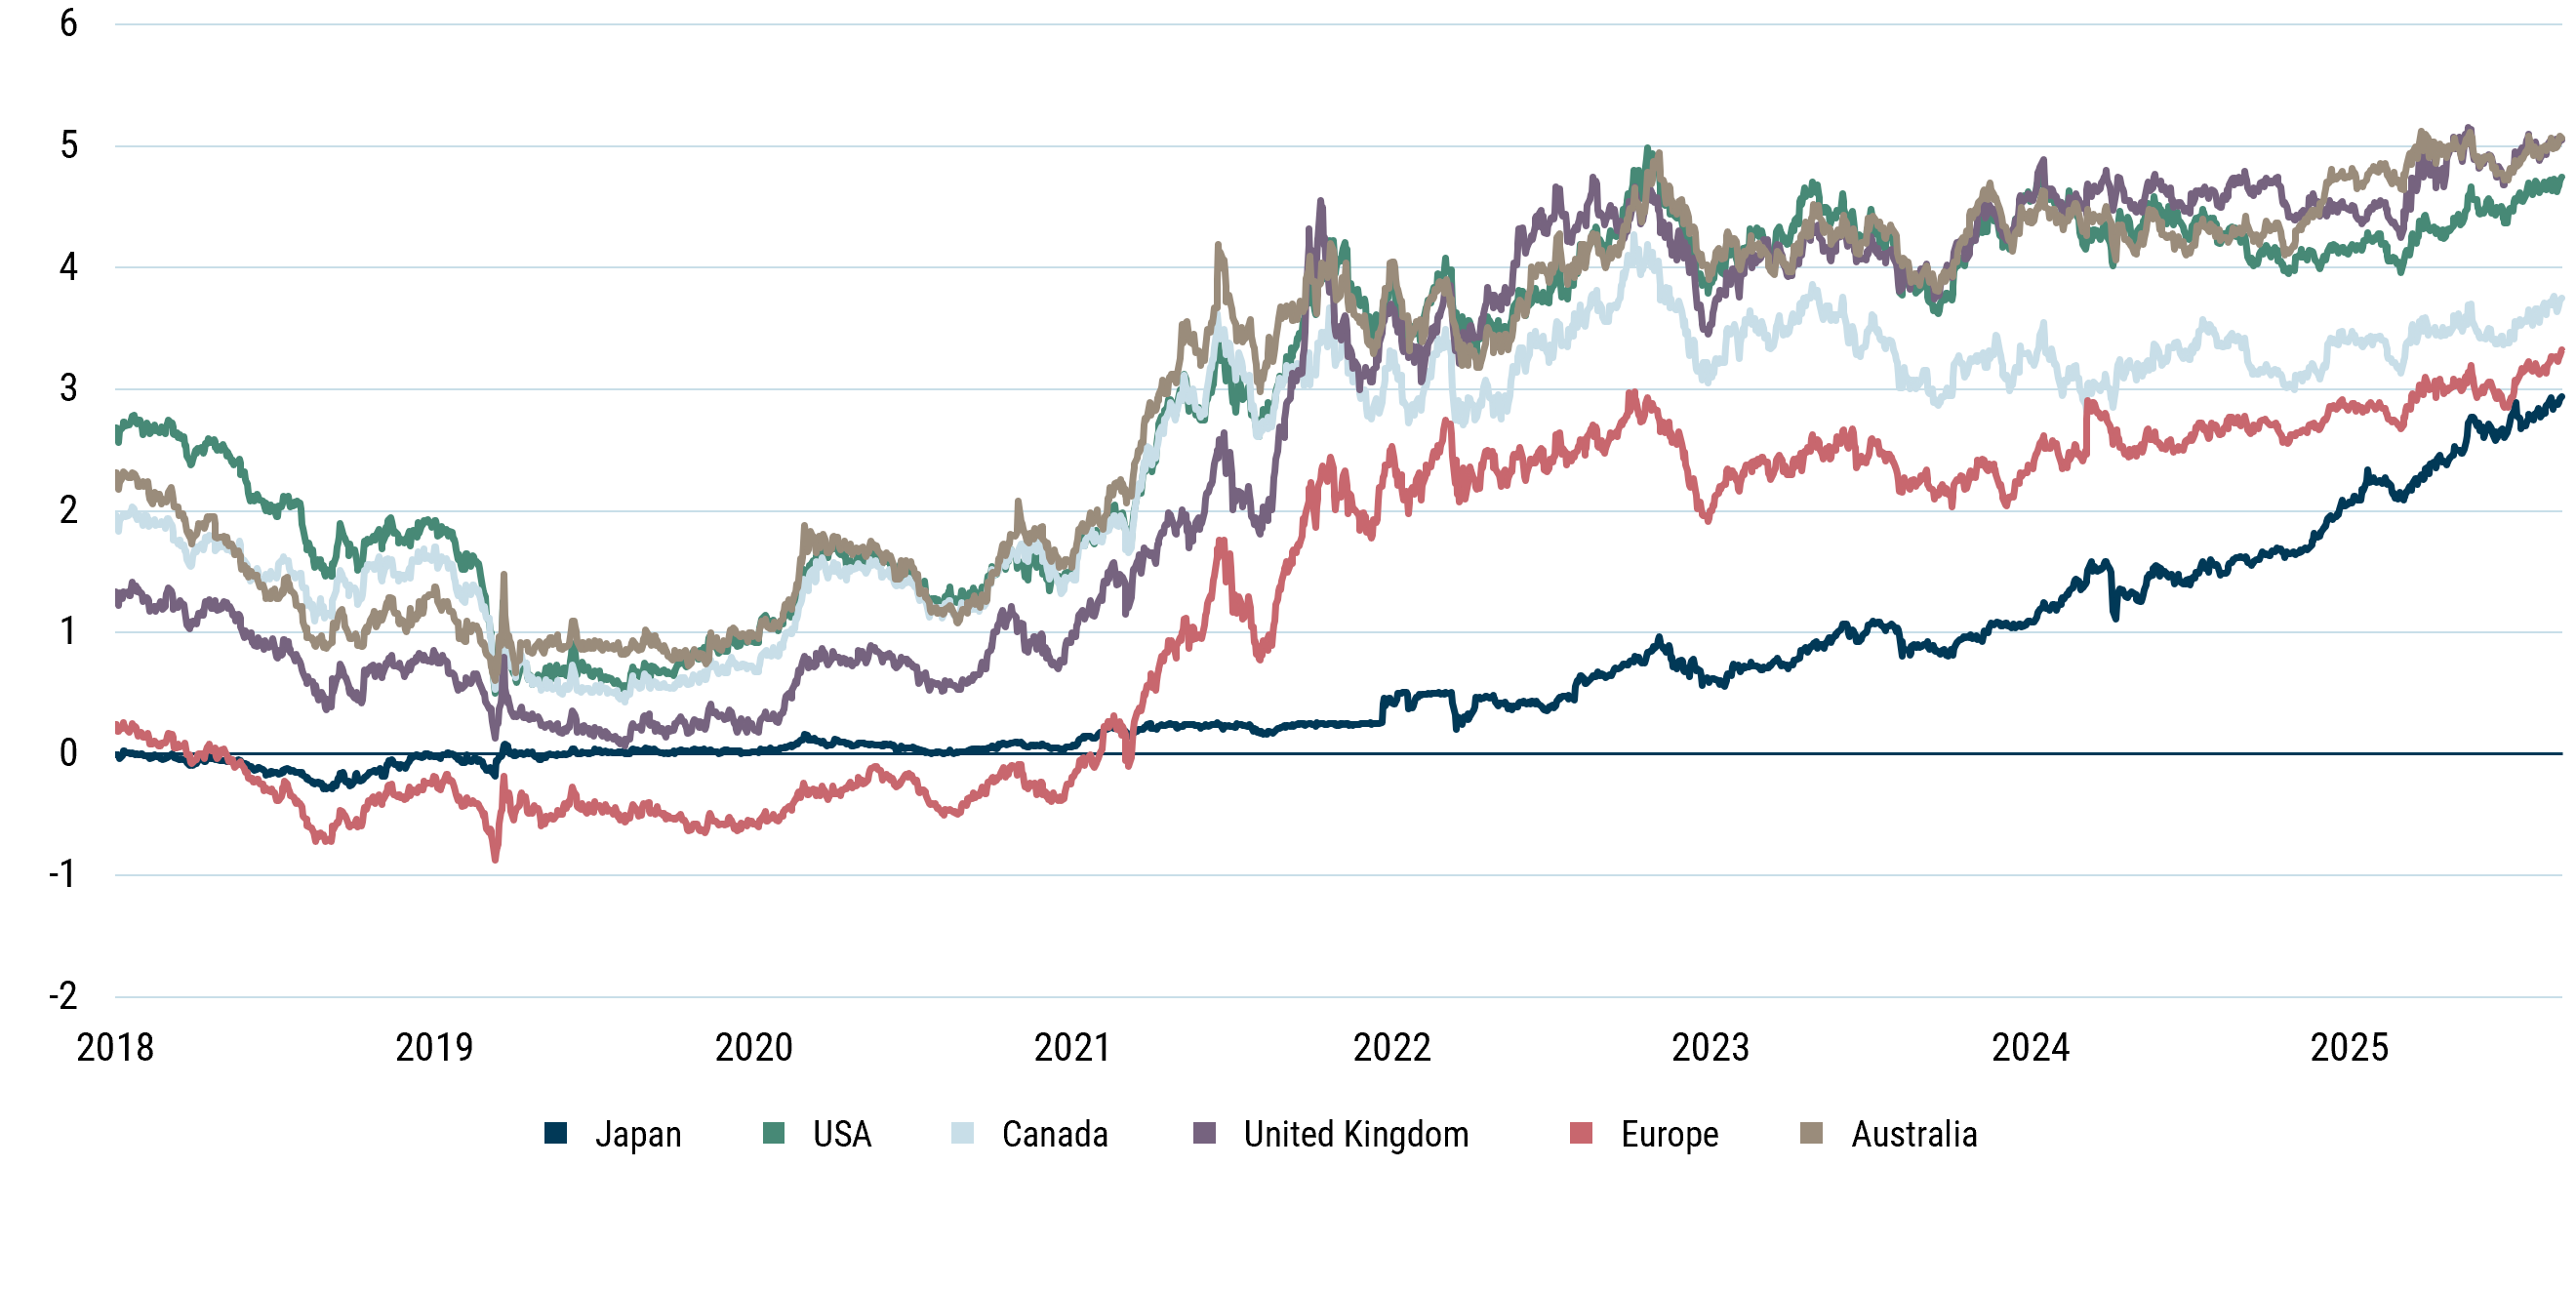
As of 8/31/2026 | Source: Factset, GMO
Together, these forces have contributed to a marked change in expectations for U.S. monetary policy. As we can see in Exhibit 2 below, at the end of the first quarter, markets had a distinctly dovish bias. That stance has since shifted materially to pricing in rate rises by the end of the year.
Exhibit 2: Change in Interest Rate Expectations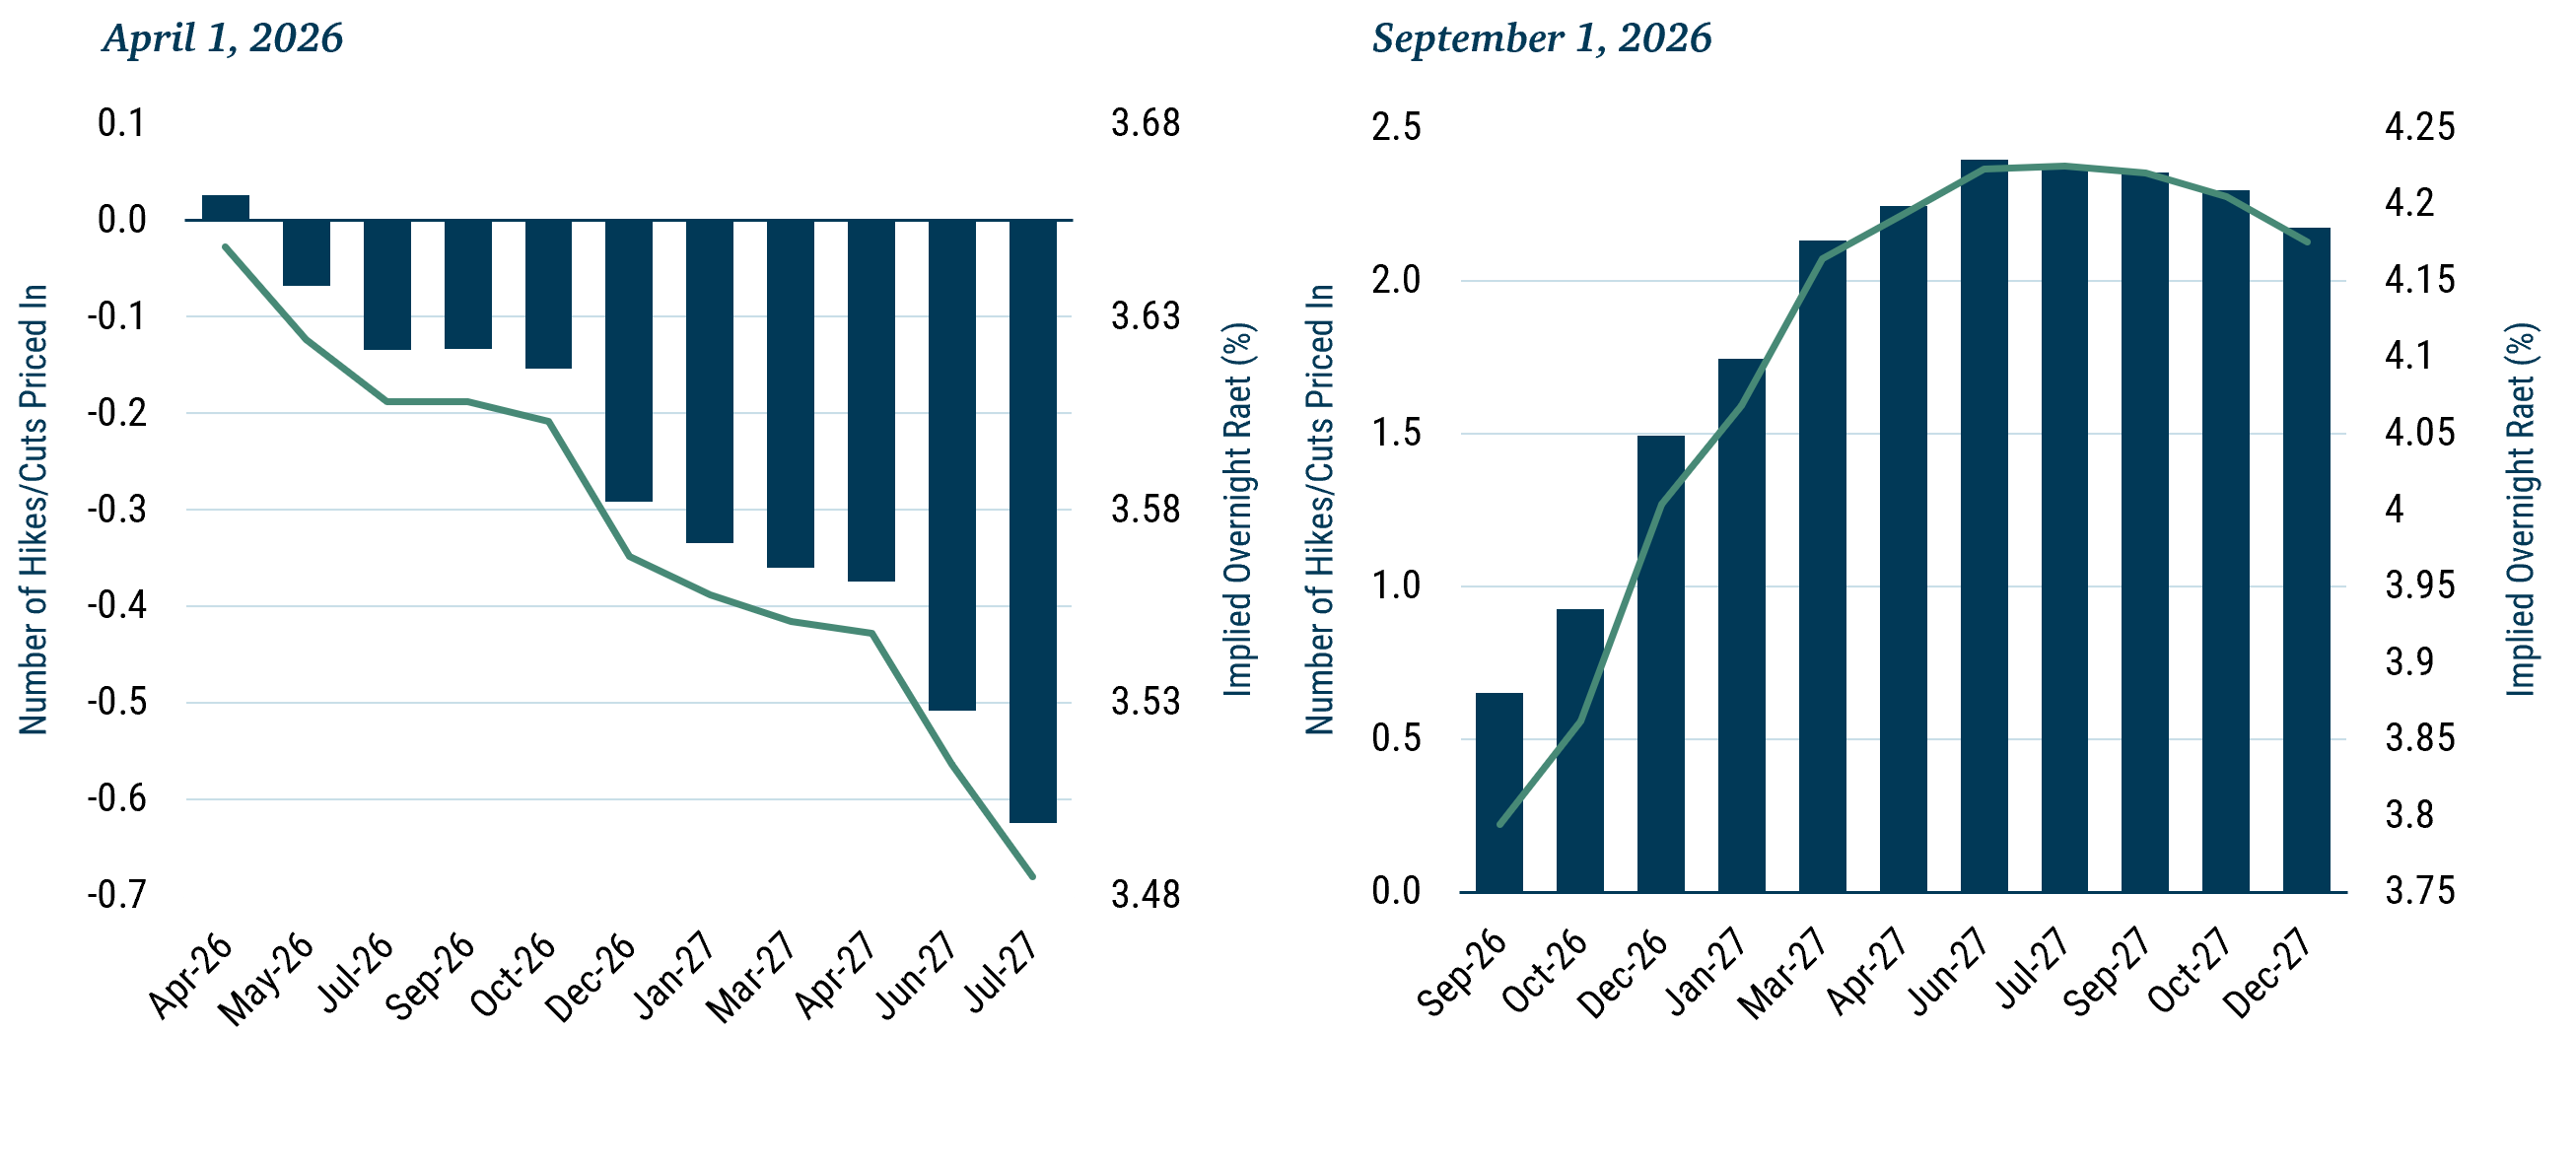
As of 8/31/2026 | Source: Bloomberg, GMO
The United States is not alone. Futures and swap curves across several major markets now imply higher policy rates, suggesting that central-bank activity may increase in the near future. The investment question is how portfolios behave when policy settings are changing, and the path is uncertain.
Central Bank Activity - Two Regimes
To assess the investment implications of a more active policy environment, we examined the number of monthly policy-rate changes across 11 central banks: the G10 economies plus India. We included India alongside the G10 countries because its interest-rate swap market is sufficiently liquid to allow us to compare market-implied expectations.
As we can see in Exhibit 3, central bank activity has historically occurred in cycles. Between 2010 and 2020, policy changes were relatively infrequent, with only one or two central banks typically moving in a given month. By contrast, the 2022-2024 period featured a much higher concentration of policy changes as central banks responded to the post-pandemic inflation shock. We therefore categorize the data into two regimes.
Exhibit 3: Number of Central Banks Changing Rates (Quarterly)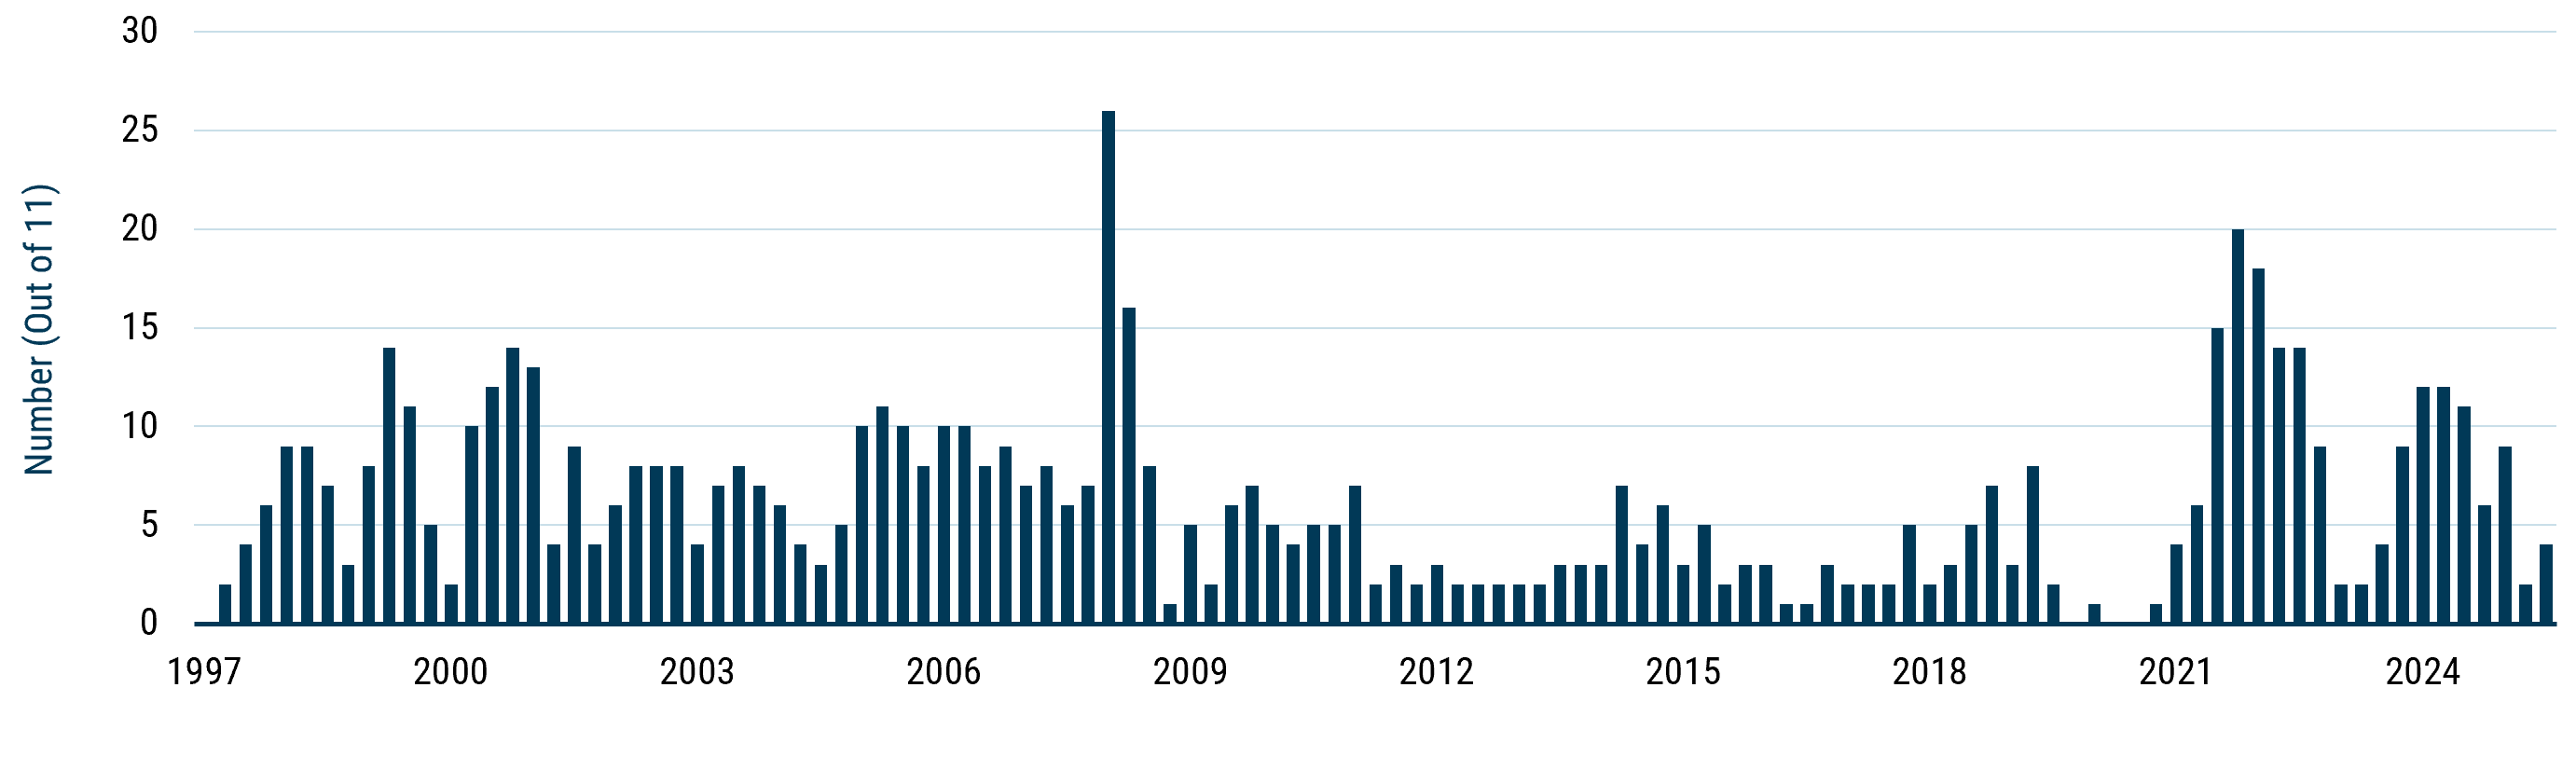
As of 8/31/2026 | Source: Factset, GMO
Impact on Returns
For comparison, the monthly returns for the MSCI World Index (USD), the Bloomberg Global Aggregate, the HFRX Macro Index, and GMO’s Systematic Global Macro Strategy (SGM) (net returns) were observed since December 1997 (the start of the HFRX index), except for SGM, which commenced in 2002. They were divided into two regimes:
- Passive Regime: months with one or fewer central bank move (50% of observations)
- Active Regime: months with more than one central bank move (50% of observations)
For completeness, the “Active Regime” was further split into 3 subgroups:
- More than one change up (10% of observations)
- More than one change down (18% of observations)
- More than one change in any direction (22% of observations)While we have run various regressions with a range of control variables to confirm the results and conclusions, for ease of reference we show average returns across the different regimes.
The results are notable. Growth assets have historically struggled when central-bank activity is elevated, regardless of the direction of policy changes. As observed in Exhibit 4 below, equity returns were lower in both directional sub-regimes (reflecting both up and down moves), averaging 25bp in months with multiple increases and 13bp in months with multiple decreases, compared with 124bp in passive regime months.
Perhaps of equal concern for investors is that when central banks are active, bond market performance is worse in three of the four regimes (and in some cases, statistically so). This suggests that those relying on bonds to provide a diversifying hedge against equities may experience disappointing results.
By contrast, both the macro fund and the macro index have historically delivered returns that, on average, are stronger (or at least unaffected) by central bank activity. These results indicate that macro-themed exposures can be an effective hedge against this type of economic activity.
This outcome is economically intuitive and is further supported by other authors, who have reported similar results. Macro strategies have demonstrated resilience amid changes in interest-rate carry, shifts in yield direction, and policy-path divergence across countries. They can also adjust equity exposure more flexibly than long-only portfolios, potentially creating a differentiated source of returns when policy uncertainty disrupts traditional markets. Equities tend to do better in benign central bank environments; macro tends to shine during periods of active central bank policy.
Exhibit 4: Average Monthly Returns and Global Policy Changes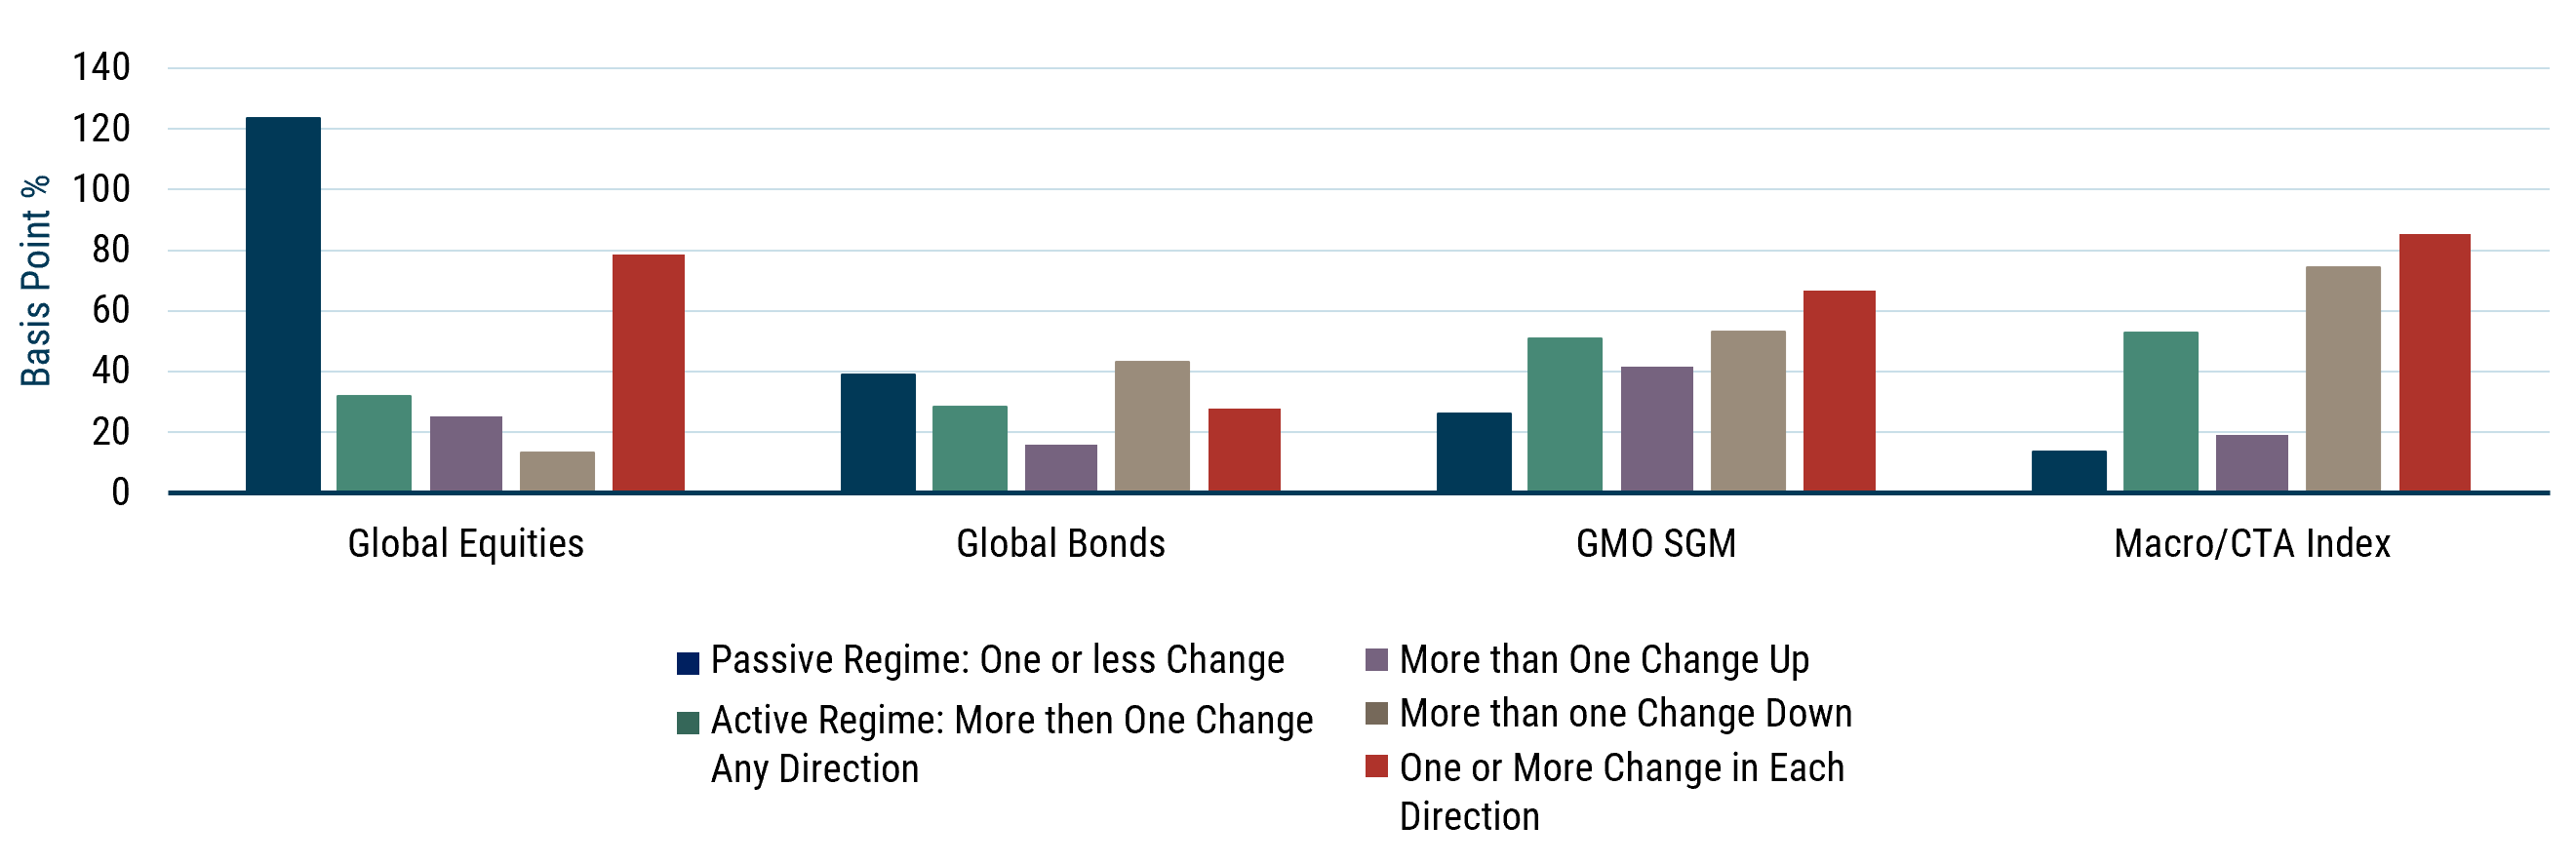
As of 8/31/2026 | Source: Bloomberg, Factset, HFRX, GMO
Why This Matters for Investors Now
The most immediate reason for investors to consider this issue is that markets are pricing in potential rate increases across most markets in our sample. Across the G10 plus India, nine markets currently imply at least one 25 bp-equivalent increase by year-end, with more moves in the near future. While each individual market forecast is prone to some degree of error, collectively, they signal that central bank activity is most likely to rise.
The table below summarizes the number of 25 bp-equivalent policy moves implied by Bloomberg rate models. Positive values indicate implied increases; negative values indicate implied cuts.
Exhibit 5: Implied 25bp-equivalent moves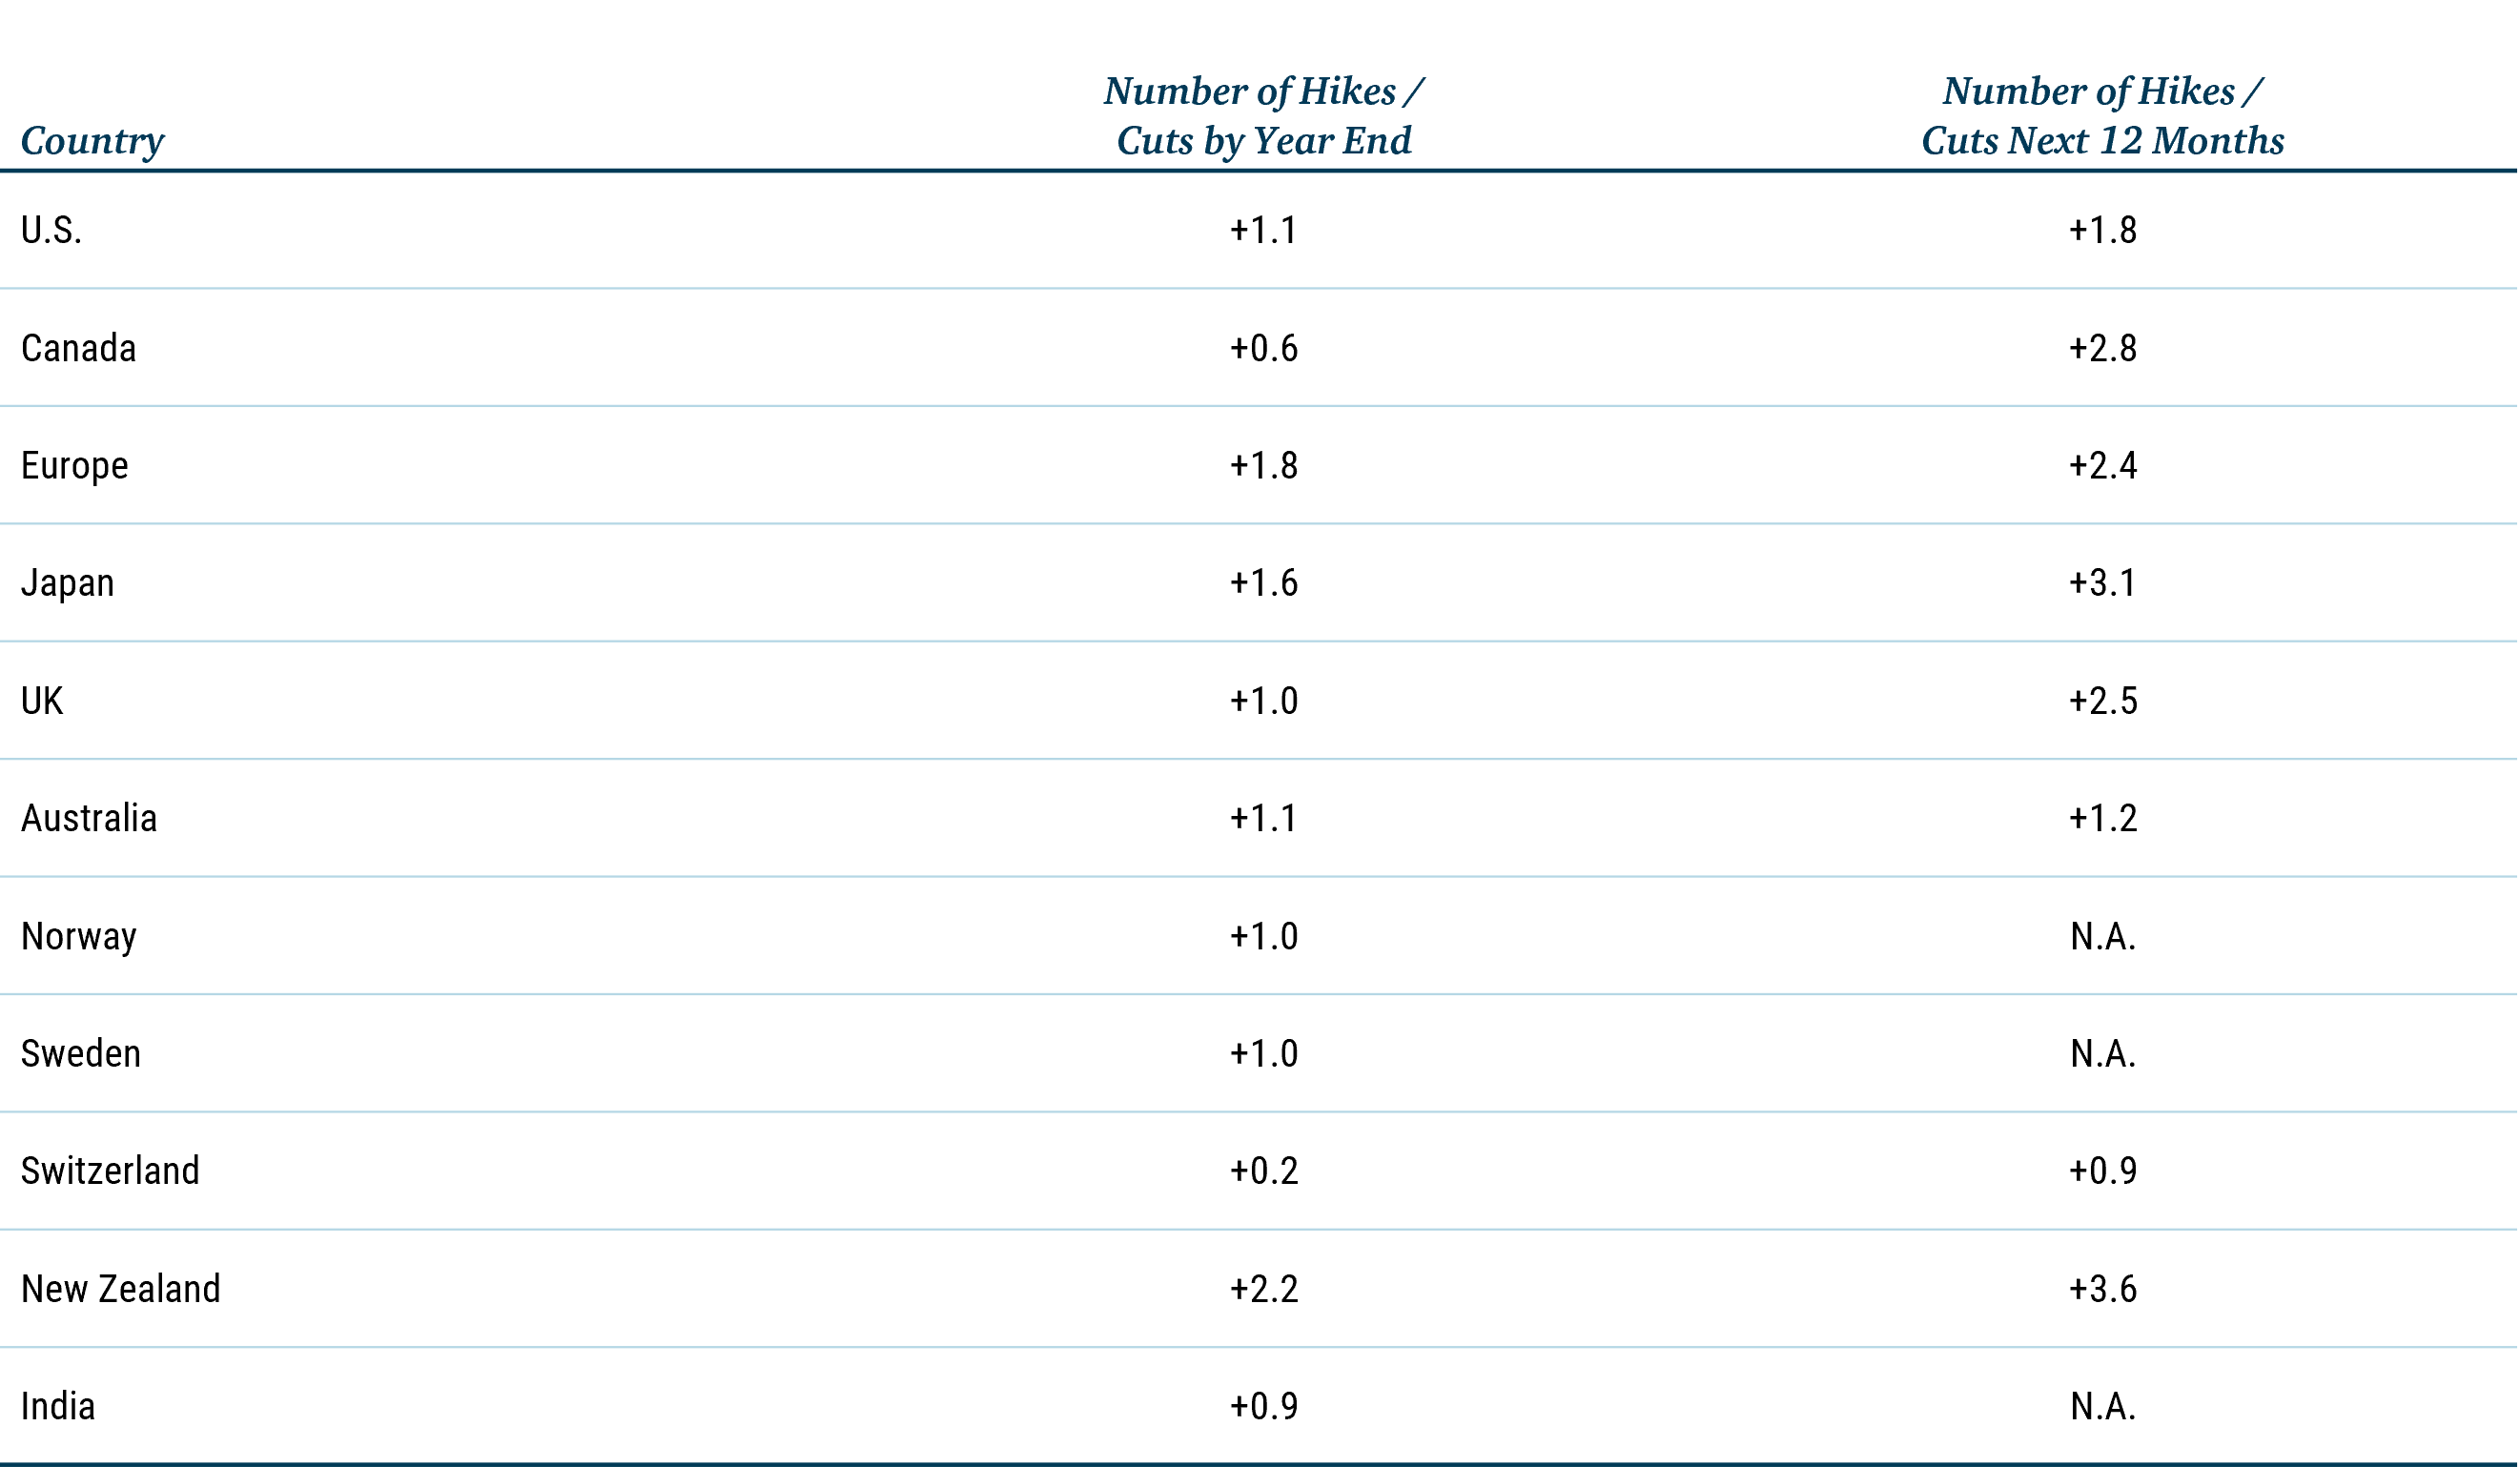
As of 8/31/2026 | Source: Bloomberg, GMO
What’s more, economists’ forecasts suggest that elevated central bank activity is likely to persist throughout 2027. According to Bloomberg consensus estimates, economists collectively expect around a dozen policy rate changes across major central banks during the year, with several institutions potentially reversing course over the period. While we do not necessarily share these forecasts, they nevertheless point to an environment characterized by sustained central bank activity and, potentially, heightened monetary policy uncertainty.
Does Policy Uncertainty Matter?
An initial conclusion to the results above is that the direction of policy moves matters less than whether central banks are active at all. However, does monetary policy uncertainty matter, and can it be measured?
The perception of greater uncertainty is intuitive, but it is important to assess it systematically. Even if it isn’t a global measure, one way to look at this is the Market-Based Monetary Policy Uncertainty index, published by the Federal Reserve Bank of San Francisco. Conceptually similar to the CBOE Volatility Index (VIX), the measure uses pricing from short-term interest-rate derivatives to estimate the degree of uncertainty embedded in market expectations for monetary policy.
The market-based measure has risen again in recent months after retreating from an earlier peak. More importantly, it remains elevated relative to much of the past 15 years.
For those interested, there is a secondary qualitative measure (though perhaps less accurate) also published by the St. Louis Federal Reserve. The Baker, Bloom, and Davis Economic Policy Uncertainty index, available via FRED, measures uncertainty based on newspaper coverage rather than market pricing and is therefore less directly tied to tradable expectations. Yet, it, too, remains elevated after recent moderation.
(Please see References at the bottom of the page for more details about these indices.)
Exhibit 6: Market-Based Monetary Policy Uncertainty (12 months Forward)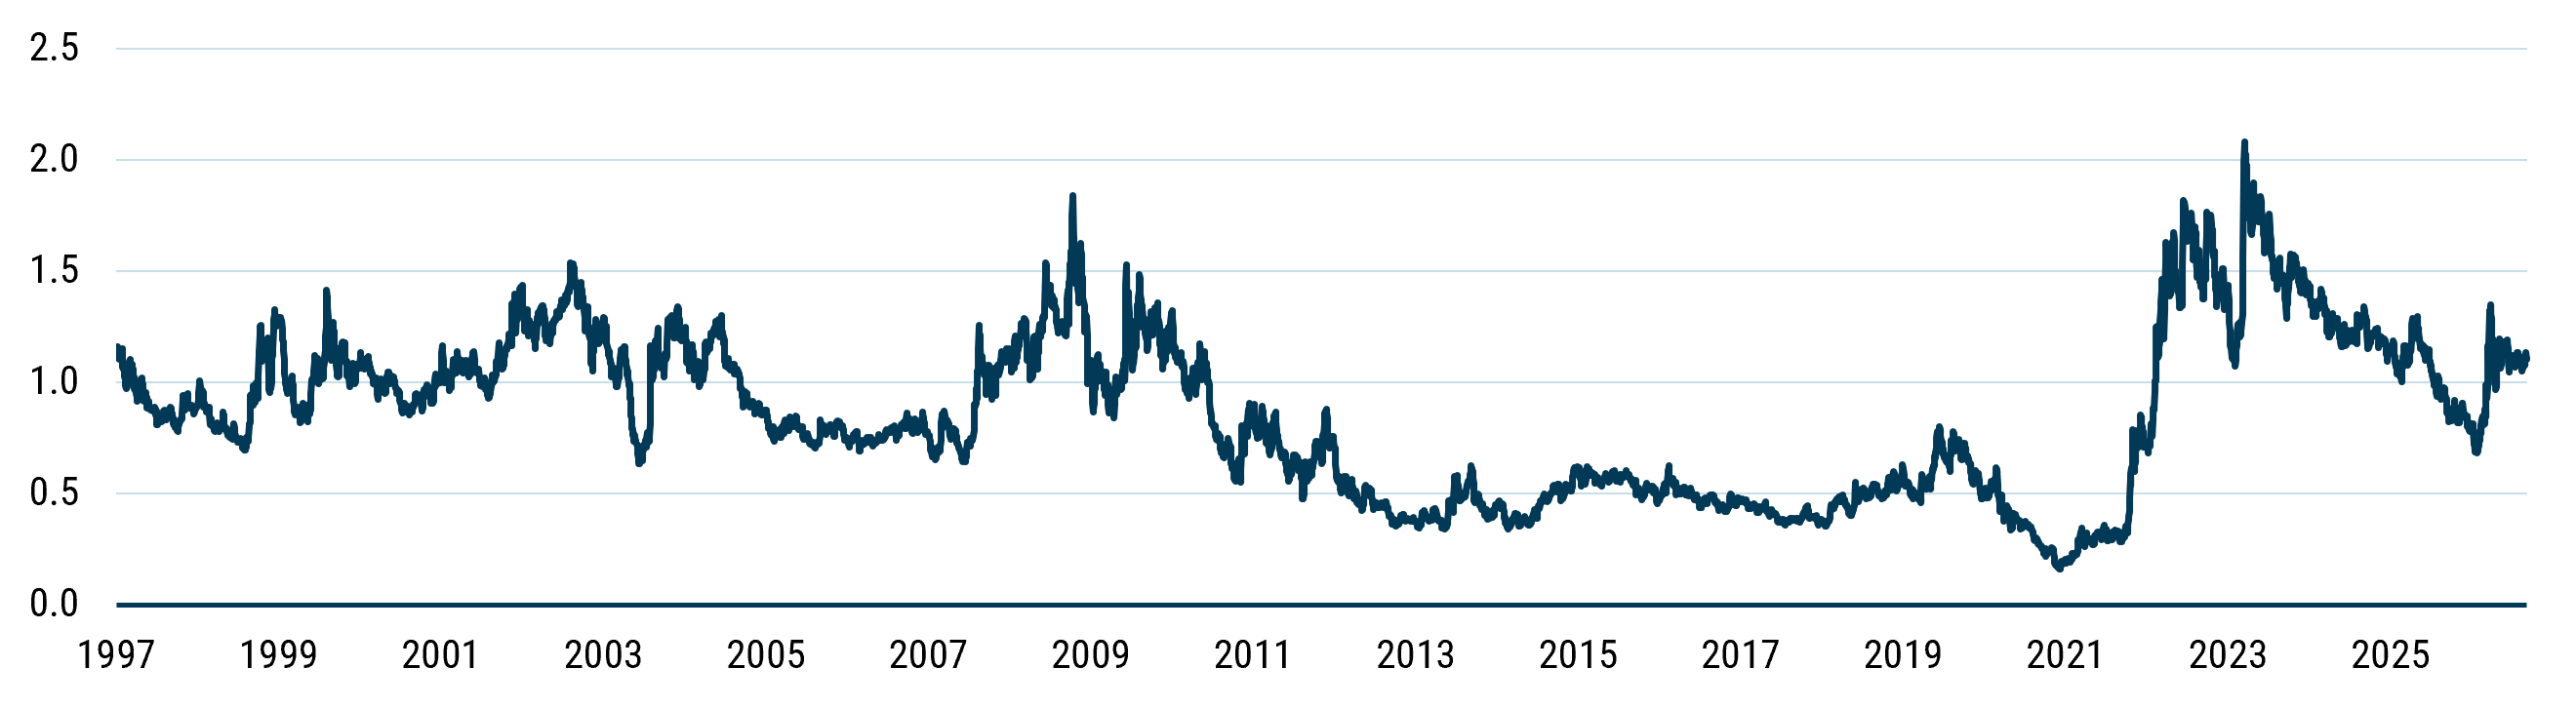
As of 8/31/2026 | Source: Federal Reserve Bank of San Francisco
For the regime analysis below, we focused on the market-based measure because it reflects traded prices and is therefore closely linked to the rate expectations discussed above. We classified months as “higher uncertainty” or “lower uncertainty” depending on whether the index was above or below its full-sample median.
Exhibit 7: Average Monthly Returns and Market-based Monetary Policy Uncertainty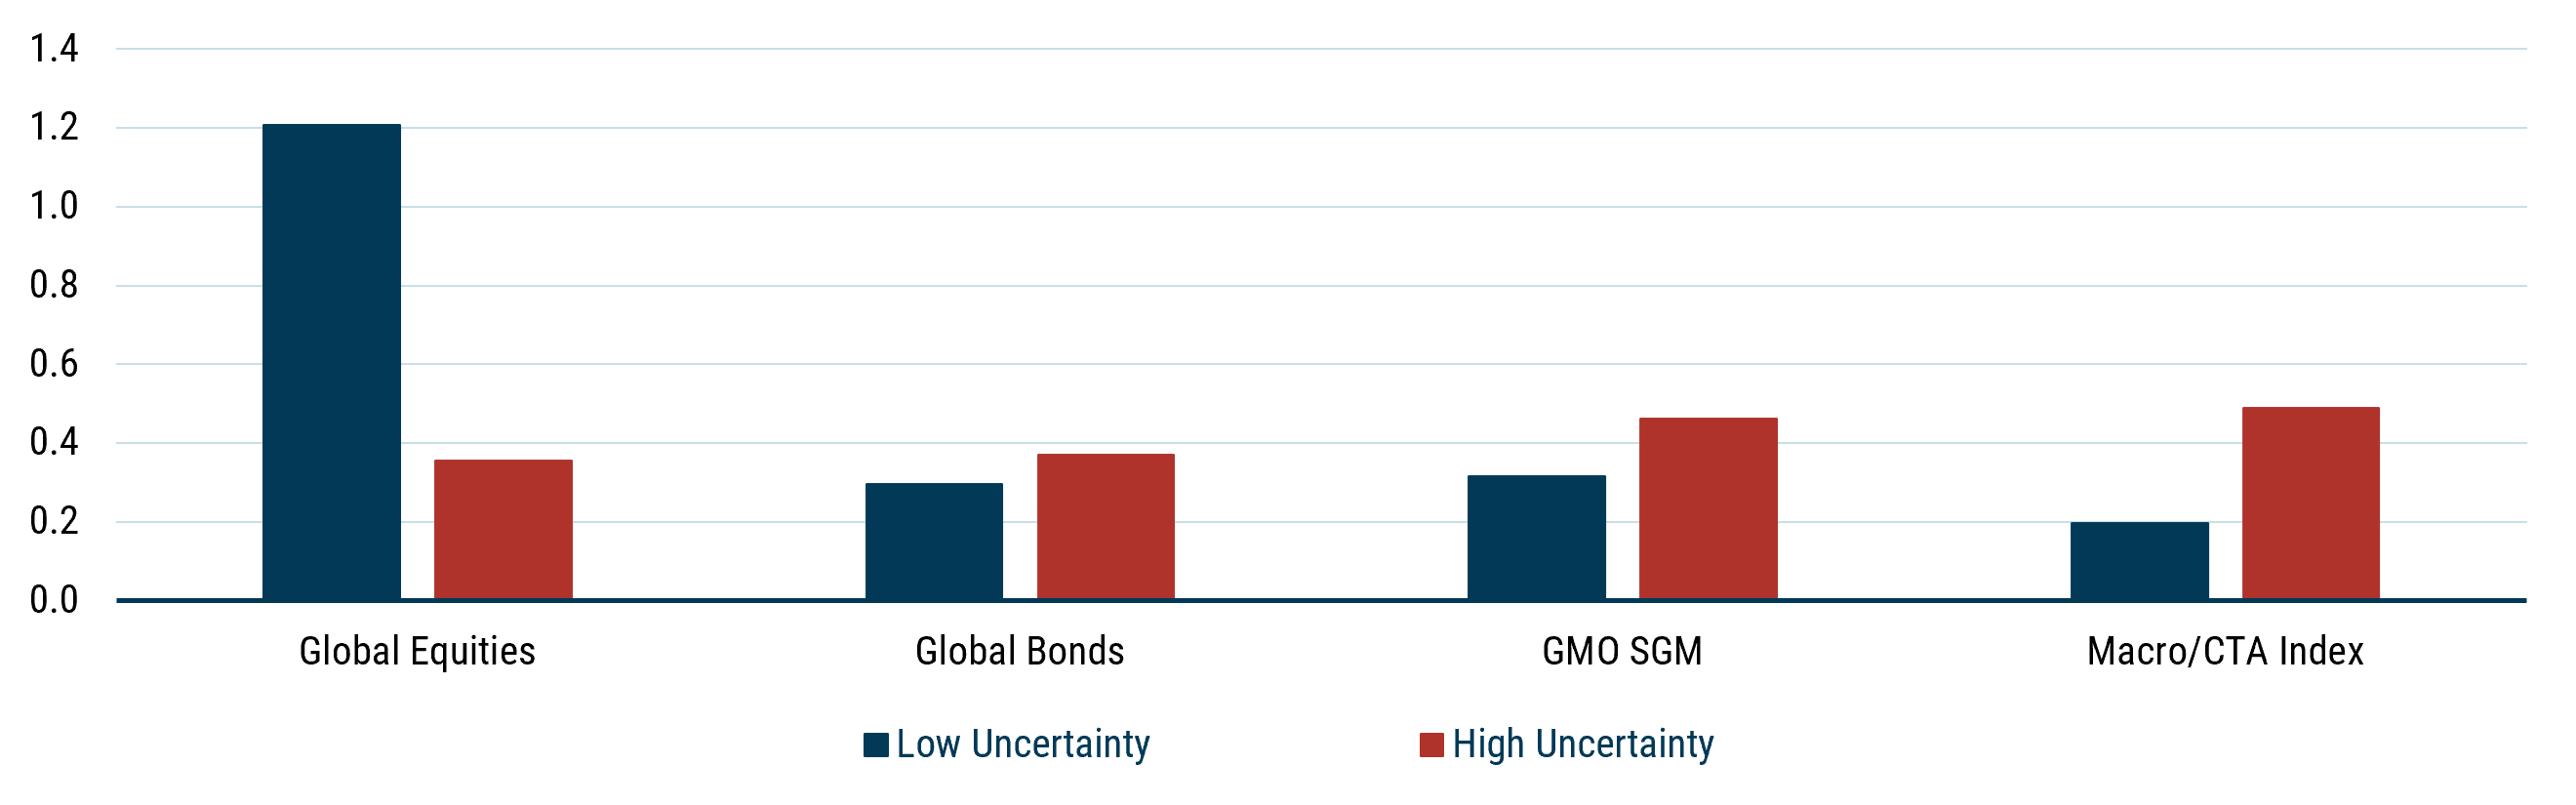
As of August 2026 | Source: Bloomberg, Factset, HFRX, GMO
The results corroborate the central bank activity analysis. Equities have historically delivered weaker returns during periods of higher uncertainty, and statistical results strongly support this. Meanwhile, the results for macro strategies suggest that they are at least indifferent to central bank uncertainty regimes.
Taken together, the two analyses point to the same conclusion: macro strategies find opportunity where policy expectations, yield curves, and cross-country rate paths are in motion.
The portfolio implication can be of critical importance for investors. When central banks are active and uncertainty remains elevated, traditional equity and bond diversification and returns may be less reliable. At the same time, flexible macro strategies may provide a complementary source of returns.
In Conclusion
It is difficult to see a rapid return to a clear and stable global policy environment. Inflation remains persistent, market expectations are shifting, sovereign debt and market functioning are attracting greater scrutiny, and geopolitical developments continue to complicate central-bank reaction functions. At the same time, central banks are beginning to respond.
These conditions have historically been challenging for equities, while bonds may not provide the same degree of diversification that investors have relied upon in more stable regimes. Macro strategies can help broaden the opportunity set. Their ability to invest across asset classes, express both long and short views, and respond to changing policy paths may provide valuable diversification when uncertainty is elevated. They can be invaluable when other parts of your portfolio seem likely to struggle.
While we do not argue that this environment guarantees strong macro returns, we maintain that the conditions under which macro has historically added most, frequent policy change, and elevated uncertainty, are the conditions for which markets are currently pricing. We believe that offers reason for investors to revisit the allocation question now rather than after the fact.
At GMO we have been managing our flagship Systematic Global Macro strategy since 2002 and have a long history of managing through various market conditions. Given our long history, and an ability to be nimble, we are uniquely positioned to help clients navigate today’s evolving markets and opportunity set.
References
Baker, Scott R., Nicholas Bloom, and Steven J. Davis. Economic Policy Uncertainty Index: Categorical Index: Monetary Policy (EPUMONETARY). Federal Reserve Bank of St. Louis, FRED. Accessed October 8, 2026 https://fred.stlouisfed.org/series/EPUMONETARY.
Bauer, Michael D., Aeimit Lakdawala, and Philippe Mueller. “Market-Based Monetary Policy Uncertainty.” The Economic Journal 132, no. 644 (May 2022): 1290-1308.
https://doi.org/10.1093/ej/ueab086
“Macro Across Monetary Regimes,” Graham Capital Management, last modified January, 2025. https://www.grahamcapital.com/blog/macro-across-monetary-regimes/.